Florida Homeowners Insurance: What to Check Before You Make an Offer
If you're moving to Florida, homeowners insurance is the line item that surprises people most. It can change what a house really costs per month, and it can change which house you should buy. I'm Troy Boss, a REALTOR® with LIFESTYLE International Realty in Clermont. I'm not an insurance agent, so this is the buyer's checklist I walk clients through, plus the current numbers, and a licensed agent gives you the actual quote.
How much does homeowners insurance cost in Florida?
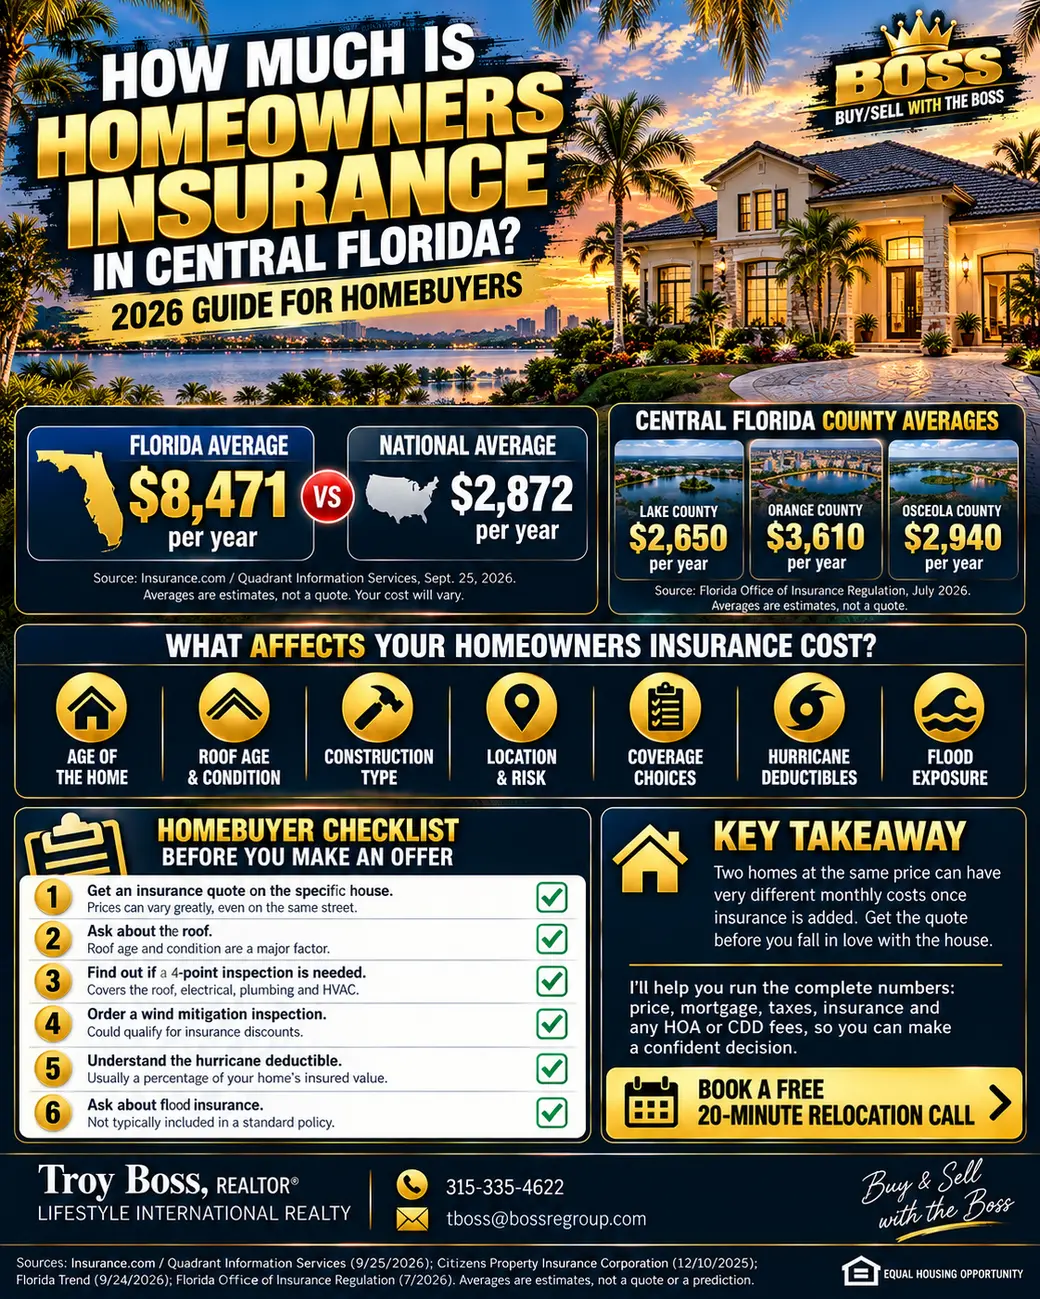
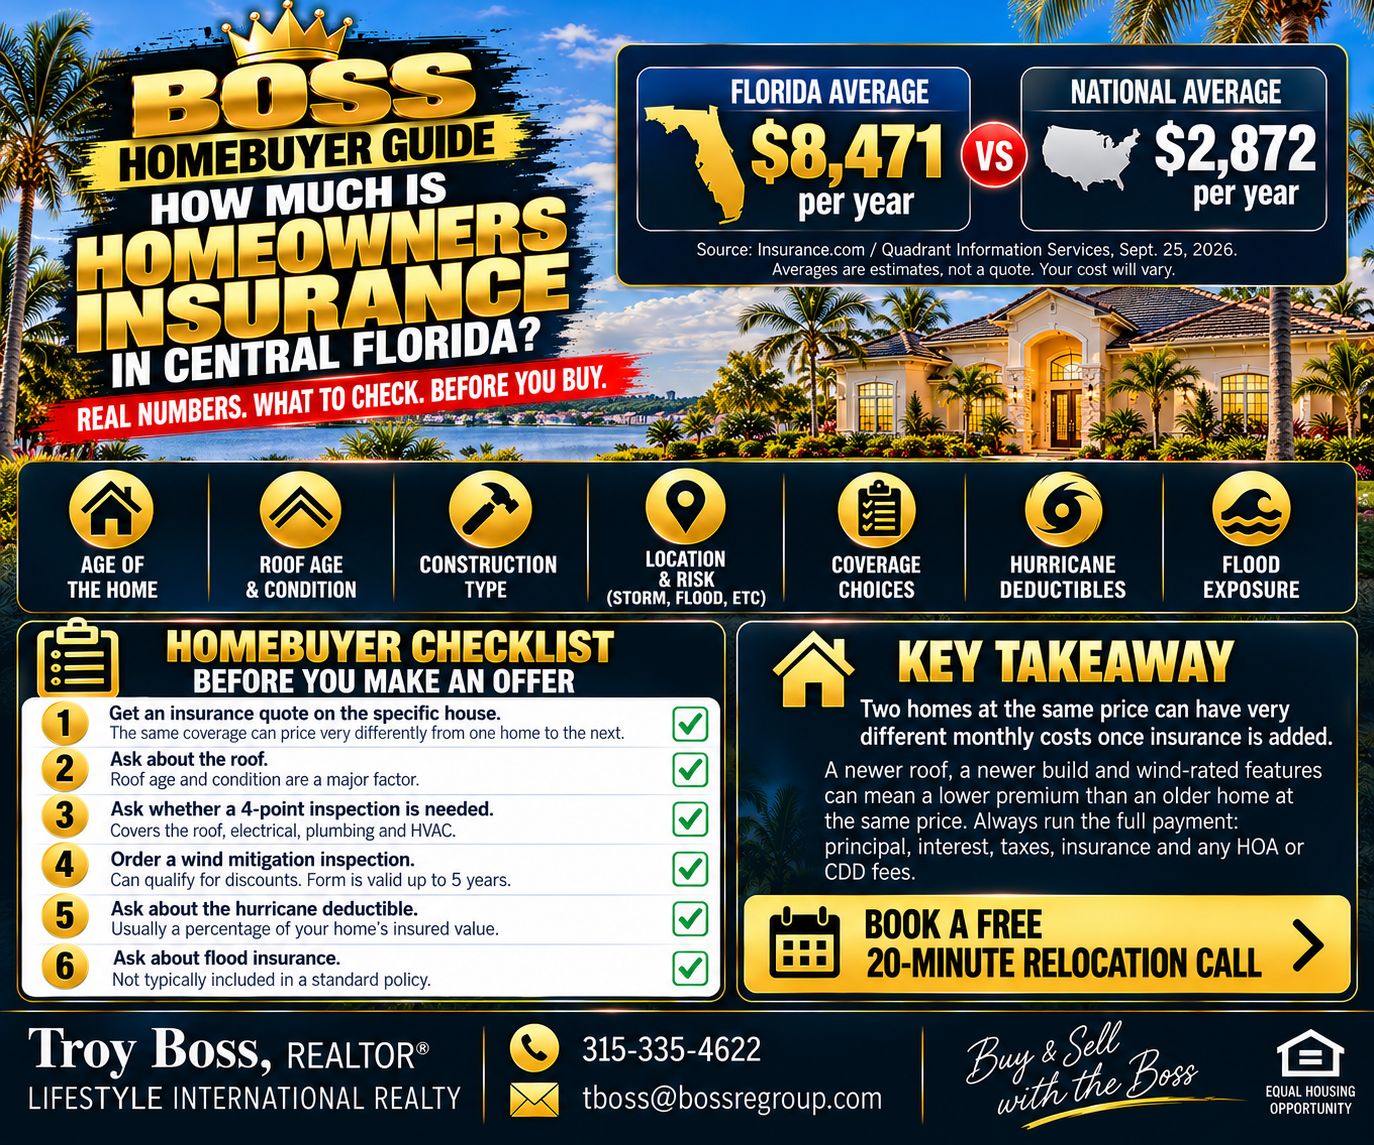
More than almost anywhere else in the country. One 2026 analysis from Insurance.com, using Quadrant Information Services data, put the statewide average at about $8,471 a year, versus about $2,872 nationally. Treat that as a ballpark, not a quote. Your number depends on the home's age, roof, construction type, location and coverage choices, and two houses on the same street can price very differently.
Is the market getting better?
Some signs point that way, with caveats. Citizens Property Insurance, the state-backed insurer of last resort, has shrunk from about 1.4 million policies in 2023 to roughly 255,000 in mid-September 2026, as policies moved to private companies. Florida's insurance commissioner said that since January 2024, 48 companies have filed for rate decreases, 53 requested no change or an increase, and the decreases range from -0.3% to -19.7%. Citizens' board also recommended an average 2.6% decrease for 2026, its first average cut since 2015. That is good news. It is not a promise that your premium will fall, and I won't predict where rates go from here.
What should I check before making an offer?
- Get an insurance quote on the specific house. Before you're deep into the contract, ask an independent agent to quote that address. The price of the same coverage can swing a lot from one home to the next.
- Ask about the roof. Roof age and condition are among the first things insurers look at. Ask your agent what roof age their carriers will accept, then compare it to the roof on the house you want.
- Ask whether a 4-point inspection is needed. It covers the roof, electrical, plumbing and HVAC. Many insurers require one on older homes, often at 20 to 30 years or more depending on the company.
- Order a wind mitigation inspection. A licensed inspector documents features like roof shape, roof-to-wall connections and opening protection on the state's uniform form. Florida requires insurers' rate filings to include discounts for qualifying features, which can lower the wind portion of your premium. The state says the form is valid for up to five years if nothing material changes.
- Ask about the hurricane deductible. It is usually a percentage of your home's insured value, not a flat dollar amount, so know what it would be in dollars before a storm.
- Ask about flood. A standard homeowners policy generally does not include flood coverage. It is added by endorsement or bought as a separate policy, and there is typically a 30-day waiting period unless the purchase is tied to a mortgage loan. Whether your house is in a flood zone can also affect your lender's requirements.
Does this change which house I should buy?
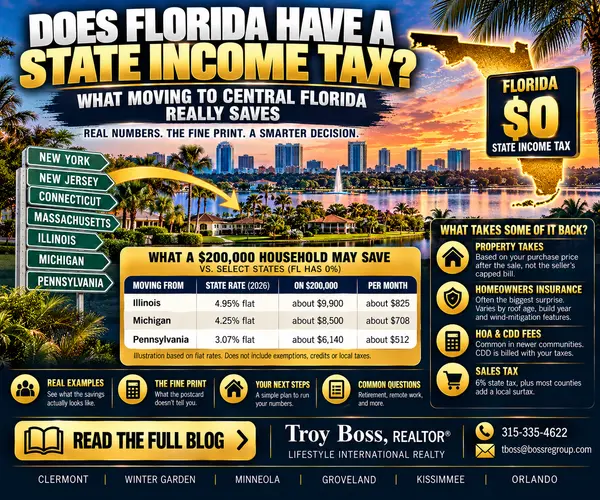
Often, yes. Two homes at the same price can have very different monthly costs once insurance is added. A newer roof, a newer build and wind-rated features can mean a lower premium than an older house at the same price. Run the full payment, principal, interest, taxes, insurance and any HOA or CDD fees, on each house you're seriously considering. I cover the other side of the budget in my guide on what no state income tax really saves and the fees that come with newer communities in HOA and CDD fees in Clermont.
Common questions
Can I just keep my insurance from my old state?
Not for a Florida home. Your policy is written for the specific property, so you'll need a Florida policy that covers wind, and your lender will require proof of coverage before closing.
Should I use Citizens?
Citizens is meant to be the insurer of last resort, so ask your agent whether private options are available first. Rules and eligibility change, so confirm with a licensed agent.
When should I get the quote?
As early as you can, ideally before your inspection period ends, so you can still adjust your plans if the numbers surprise you.
Is now a good time to buy?
That depends on your budget and timeline, and the full picture is in my relocation guide. What I can tell you is that you should price the insurance before you fall in love with the house.
Want to run the numbers on a specific house? I'll walk you through your budget, your towns and your timeline in 20 minutes, with no pressure, and I'll connect you with independent insurance agents and my lender for the actual quotes.
Book a free 20-minute relocation call
Troy Boss
REALTOR® – LIFESTYLE International Realty, Clermont
315-335-4622 · tboss@bossregroup.com
Sources: Insurance.com / Quadrant Information Services, average homeowners insurance cost by state, published September 25, 2026. Citizens Property Insurance Corporation, press release on 2026 recommended rate changes, December 10, 2025. News Service of Florida via Florida Trend, September 24, 2026 (Citizens policy count; Florida Insurance Commissioner rate-filing figures). Florida Office of Insurance Regulation, wind mitigation resources (Uniform Mitigation Verification Inspection Form). Florida Department of Financial Services, flood insurance overview. Averages and filings change; figures are as of the dates shown and are not a quote or a prediction. This guide is general information, not insurance, tax or legal advice. Confirm your coverage and cost with a licensed Florida insurance agent.
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "