The 50-Year Mortgage: A Bold New Idea or a Financial Trap?
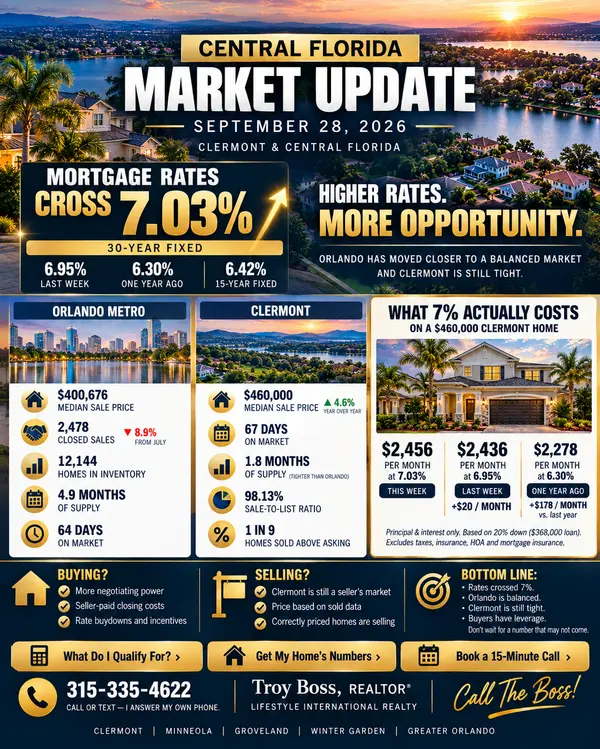
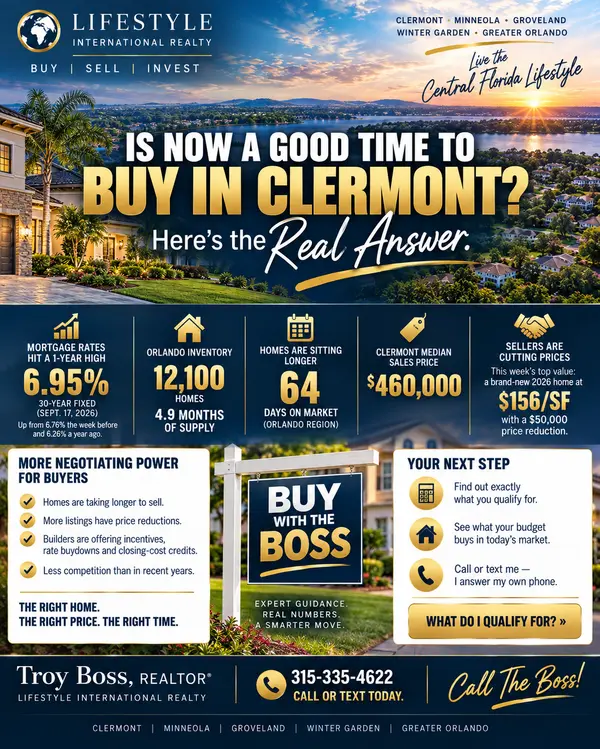
As housing prices climb and affordability continues to challenge buyers, the idea of a 50-year mortgage is gaining traction in conversations about real estate financing. While it’s not yet a mainstream option in the U.S., several global markets and private lenders have explored extended loan terms to make homeownership more accessible. But does stretching your mortgage over half a century really make sense?
Let’s break down the pros and cons of the 50-year mortgage so you can decide whether it’s a visionary solution—or a long-term burden.
🔹 The Pros of a 50-Year Mortgage
1. Lower Monthly Payments
The most obvious benefit is affordability. Extending your loan term spreads out the payments, significantly reducing your monthly bill. This could make it easier for first-time buyers or those in high-cost markets to enter the housing market without stretching their budgets to the limit.
2. Increased Buying Power
Lower monthly payments can also mean you qualify for a larger loan amount, allowing you to buy a home that might otherwise be out of reach. For many buyers, this could mean the difference between settling for a condo and purchasing a single-family home.
3. Potential Flexibility for Investors
Real estate investors who rely on cash flow might find value in the lower payments of a 50-year mortgage. With reduced monthly obligations, investors could potentially generate higher net rental income, especially in markets with strong appreciation.
4. More Stability in Expensive Markets
In places like California or Florida where prices have surged, a longer loan term could offer a way to maintain stability without resorting to risky adjustable-rate loans.
🔻 The Cons of a 50-Year Mortgage
1. Higher Lifetime Interest Costs
While your payments may be smaller, the total interest paid over 50 years would be enormous. In some cases, you might pay more than double the home’s original price by the time the mortgage is fully repaid.
2. Slower Equity Growth
Because your early payments mostly go toward interest, building equity takes decades, not years. That can limit financial flexibility if you ever want to refinance, take out a home equity loan, or sell.
3. Risk of Being “House Poor” for Life
A 50-year term might make homeownership accessible, but it also ties you to long-term debt well into retirement. You could find yourself still making mortgage payments when you’re ready to stop working.
4. Limited Availability and Uncertain Terms
Most lenders don’t currently offer 50-year mortgages, and if they did, they might come with higher interest rates or stricter conditions. Government-backed programs like FHA or VA loans are unlikely to support such long terms anytime soon.
⚖️ The Bottom Line
A 50-year mortgage could be a temporary affordability solution, but it’s not without major trade-offs. For first-time buyers, it may open the door to homeownership—but at the cost of long-term financial freedom. For investors, it could enhance cash flow but limit appreciation gains over time.
In short: a 50-year mortgage might ease the pain now but stretch the burden for decades. If you’re considering this route, talk to a trusted lender or financial advisor to explore alternatives like rate buydowns, shared equity programs, or adjustable-rate loans that might offer a better balance of affordability and sustainability.
BUY WITH THE ‘BOSS’ | 315-335-4622 | troyb.lifestyleir.com
Would you like me to make this version SEO-optimized for your Clermont, FL market (for example: “50-year mortgage in Clermont real estate”) with keywords and a meta description for posting on your website?